Last winter, my neighbor’s Beagle, Bruno, ate a piece of chicken bone. At 1:30 AM they were at the emergency clinic. The vet said, “We need surgery, right now. It’ll be $5,200.”
They didn’t have insurance. They had to put half of it on a credit card.
I had insurance for my own dog, Milo. Same month Milo had a severe allergy and ear infection. Bill was $1,400. I paid only $280.
That’s the real difference. Insurance isn’t about paperwork. It’s about that one night when you don’t want to think about money.
So let’s talk honestly about what actually makes sense in 2026.
The Two Options, Without The Fancy Words
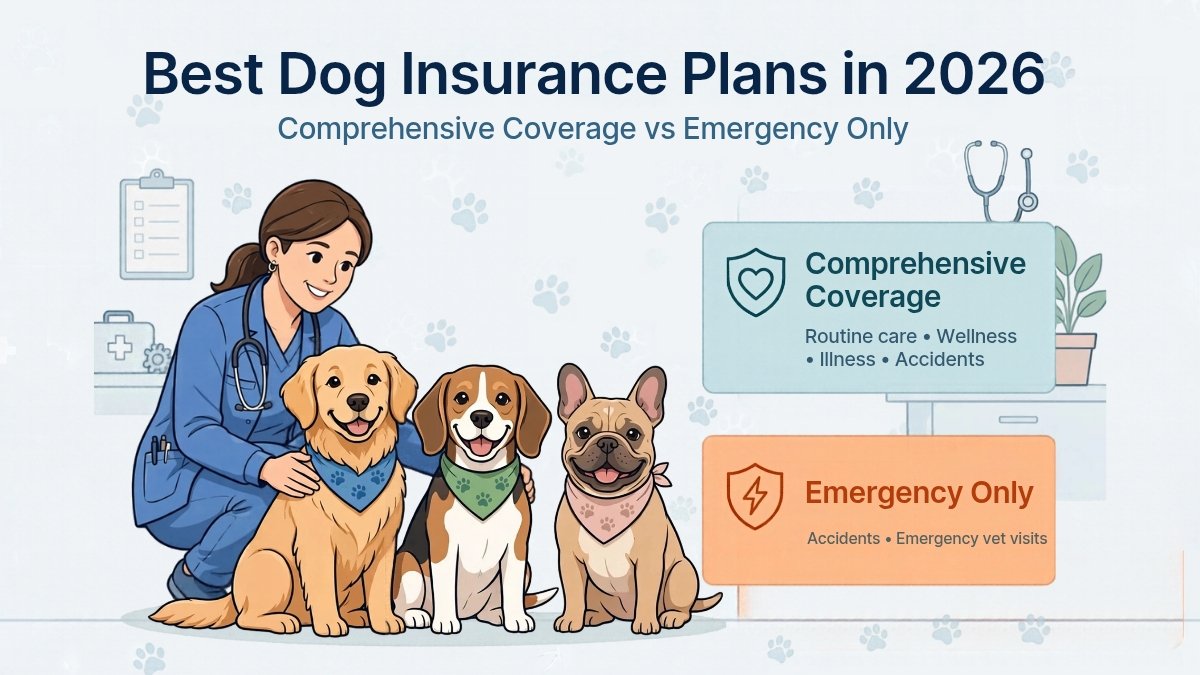
1. Comprehensive Coverage
This is the one that covers almost everything. If your dog breaks his leg running in the park – covered. If he suddenly stops eating and turns out to be a stomach infection – covered. If at age 5 he is diagnosed with cancer – covered.
It includes X-rays, blood tests, MRI, surgery, hospital stay, medicines. The stuff that actually empties your wallet.
I always tell new puppy parents – if your dog is young, this is the one. Because puppies… they eat socks, they get rashes, they get diarrhea for no reason. And breeds like French Bulldogs, Goldens, German Shepherds, they almost always need this.https://petkingdom.site/how-to-treat-canine-separation-anxiety/
2. Emergency-Only Coverage
This one is very simple. It only helps in an accident. Car hit, fall from stairs, swallowing poison, a fight with another dog. If it’s a sudden physical accident – they pay.
But if your dog wakes up vomiting, or has a skin allergy, or keeps scratching his ears, or gets cancer – they will say sorry, this is illness, not accident. Not covered.
It’s cheap. $20 a month type cheap. But it’s also half protection. I have seen people buy it thinking “at least I’m covered for illness” and then get shocked at the clinic.
Let’s Talk Money – Real 2026 Prices
I called 5 companies last month for Milo, just to check. This is what it actually looks like:
- Comprehensive is around $45 to $80 a month for a young healthy dog. For a Bulldog or older dog, it can go to $120+.
- Emergency-only is $19 to $35 a month. That’s it.
But here’s the math that matters: One ACL surgery for a dog in the US in 2026 is $4,500 to $7,000. One night in an emergency hospital is $1,500 to $3,000.
With comprehensive, you pay $250 deductible and they pay 80-90% of the rest.
With emergency-only, if it’s an illness, you pay 100% yourself.
So What Should YOU Get?
I’ll be straight with you.
If your dog is under 7, and you can afford $60 a month, get comprehensive. Get 80% reimbursement, $15k annual limit, $250 deductible. That’s the sweet spot. If you can stretch to 90%, even better. On a $6,000 bill, that extra 10% saves you $600 instantly.
Don’t think about it as a monthly expense. Think about it as you never having to say “we can’t afford the treatment.”
If your dog is very old, like 11 or 12, comprehensive becomes crazy expensive. Companies quote 180-250 a month. In that case, emergency-only is a smart, kind choice. Take that $25 plan, and put $40 aside in a separate account for him every month. That’s what my aunt does for her 12-year-old Lab.
And if you are a student or really tight on budget right now – please, get at least emergency-only. Because doing nothing is the worst option. Something is always better than watching your dog in pain and having no help at all.
Before You Buy, Please Check These 3 Things
I learned these the hard way.
- Buy it when he is healthy. If he already had an ear infection last month and you buy insurance today, they will call it “pre-existing” and never cover ear infections again.
- Ask about the waiting period. Good companies start accident cover in 2 days and illness in 14 days. If they say 30 days, walk away.
- Don’t just look at monthly price. Look at reimbursement. 90% is always better than 70%. Trust me on a big bill, that 20% difference is huge.
Your dog will never know what plan you bought. He will just know that when he was scared and in pain, you didn’t leave his side. And you could afford to stay.
Frequently Asked Questions
Is dog insurance really worth it now?
For me, yes. In the last two years, Milo had 3 issues that cost over $3,200 combined. I paid less than $700 total. But more than money, I never had to delay his treatment. That’s what peace of mind is.
I have a new puppy, what should I get?
Comprehensive, from day one. Puppy’s first year is full of stomach issues, vaccines reactions, eating random things. And if you insure early, you lock in a low price for life.
My dog is 9 years old, is it too late?
It’s not too late, but it will be costly. Get quotes for comprehensive first. If it’s over $150, get a good emergency-only plan. It will at least save you from a $5,000 accident bill.
What’s the biggest surprise with emergency-only plans?
Cancer. Most people think cancer is an emergency. Insurance doesn’t. Same with allergies and infections. These are the most common reasons dogs go to the vet, and emergency-only doesn’t cover them.
Can I change my plan later?
You can, but be careful. If your dog gets sick while on emergency-only, and then you switch to comprehensive, that sickness will be marked as pre-existing. So it still won’t be covered.
How much should I budget?
If your dog is young and healthy, keep 60-75 aside for a really good comprehensive plan. If you can only do emergency, 25-30 is enough for a decent one.
1 thought on “Best Dog Insurance Plans in 2026: Comprehensive Coverage vs Emergency Only”